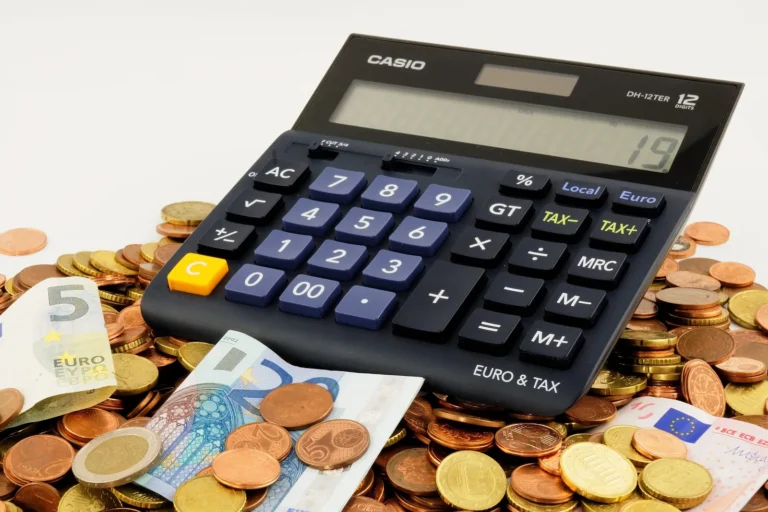
Budgeting does not have to mean tracking every coffee in a spreadsheet. The 50/30/20 rule offers a simple framework that divides your take-home pay into three buckets. It is easy to remember and flexible enough for most incomes.
How the Rule Works
The method uses your after-tax income, the amount that actually lands in your account. From there, you split it into three categories:
- 50% for needs: housing, utilities, groceries, transport, insurance and minimum debt payments.
- 30% for wants: dining out, hobbies, streaming services, travel and other lifestyle choices.
- 20% for savings and debt payoff: emergency fund contributions, retirement savings and extra debt payments.
A Simple Example
Imagine a monthly take-home income of 3,000. Under the rule, 1,500 covers needs, 900 goes to wants and 600 goes toward savings or paying down debt. Seeing those numbers side by side quickly reveals whether rent or a car payment is stretching your budget too far.
Adjusting the Percentages
In high-cost cities, needs can easily exceed half of your income. That is fine; treat the rule as a starting point rather than a strict law. You might use 60/20/20 for a while, then rebalance as your income grows or expenses fall.
The key is protecting the savings bucket. Even if wants shrink temporarily, keeping a steady savings habit builds long-term security.
Tips for Sticking With It
Review your bank statements once a month and sort spending into the three categories. Automate your savings transfer on payday so it happens first. Revisit your split whenever you get a raise or move home.
For more practical money guides, visit our finance category or browse everything new on Ztoog.com.
Conclusion
The 50/30/20 budget rule works because it is simple. It gives every part of your income a job without demanding perfection. Try it for three months, adjust where needed and watch your financial clarity improve.
This article is for educational purposes only and is not financial advice.